“It’s a pretty grim picture,” says David Miles of the Office for Budget Responsibility (OBR), describing a British economy that has seen virtually no individual growth since before the Covid pandemic. The UK is currently absorbing the secondary shocks of the US-Iran conflict, with soaring energy prices threatening to trigger a cycle of stunted growth and persistent inflation.
The UK Economic Outlook:
- Growth Slash: The OBR sharply cut its prediction for next year from 1.6% to 1% due to Middle East instability.
- Inflation Peak: Consumer prices are now projected to peak at 3.8% in 2027 as energy costs filter through supply chains.
- Rate Hikes: Interest rates, currently at 3.75%, are forecast to climb as high as 4.5% to combat stubborn inflation.
Energy Shocks Drive the 1% Growth Floor
When the OBR slashes a growth projection from 1.6% to 1%, it is a significant cut to its prediction for next year. In the raw data provided by the OBR, rising energy prices are identified as the single biggest risk to the near-term economy.
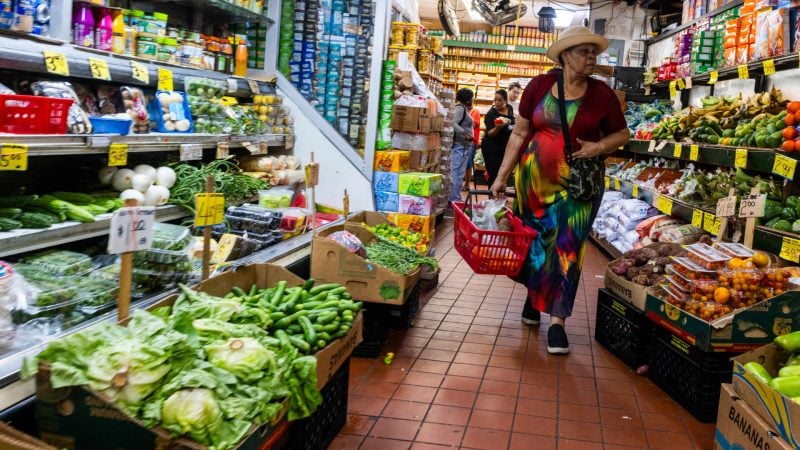
High global oil prices have already manifested at the pump, with petrol averaging nearly £1.73 per litre and diesel nearing £1.99. This isn’t just a headache for commuters. Because the UK relies heavily on road haulage, these costs act as a hidden tax on every physical good moving across the country. From produce to construction materials, the increased cost of diesel forces companies to choose between absorbing the loss or passing it to the consumer.
Most will pass it on.
Bank of England Rate Hikes Increase National Debt Costs
The Bank of England is widely expected to raise interest rates next week. Current rates sit at 3.75%, but the OBR now forecasts a ceiling of 4.5%. This pivot is a complete reversal from previous expectations of two rate cuts this year. This shift creates a double-edged sword for the British government: higher rates are necessary to cool inflation, but they simultaneously increase the cost of servicing national debt.
As debt interest payments rise, the government is forced to borrow more just to cover the interest on existing loans. Combined with higher spending on inflation-linked welfare and pensions, the fiscal headroom for the UK government is evaporating.
Institutional Sentiment and the “Small Beer” Response
Chancellor John Healey has announced policies intended to provide “breathing space” for households, but institutional analysts are unimpressed. Economists at Pantheon Macroeconomics characterized these government measures as “small beer” relative to the anticipated surge in inflation over the winter.
Institutional investors are now pricing in “significant uncertainty.” Much of the current market sentiment hinges on geopolitical variables outside of economic control. For instance, the market is closely watching US President Donald Trump’s suggestion that the conflict in the Middle East could end after next month’s mid-term elections. If the war ends, the inflationary pressure on energy eases; if it persists, the 3.8% inflation peak for 2027 may actually be an underestimate.
Living Standards in a Dismal Period
The human cost of these macro shifts is found in real household disposable income. The OBR forecasts a dip in living standards next year as energy bills erode spending power. This impact is regressive; lower-income households spend a disproportionate share of their budget on heating and fuel, meaning they feel the 3.8% inflation peak far more acutely than the wealthy.
Whether the UK can steer through these “global economic storms,” as Chancellor Healey puts it, depends entirely on the volatility of the oil market and the Bank of England’s ability to calibrate rates without triggering a deep recession.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.