Paris Burns as Fiscal Reality Collides With Public Debt Pressures
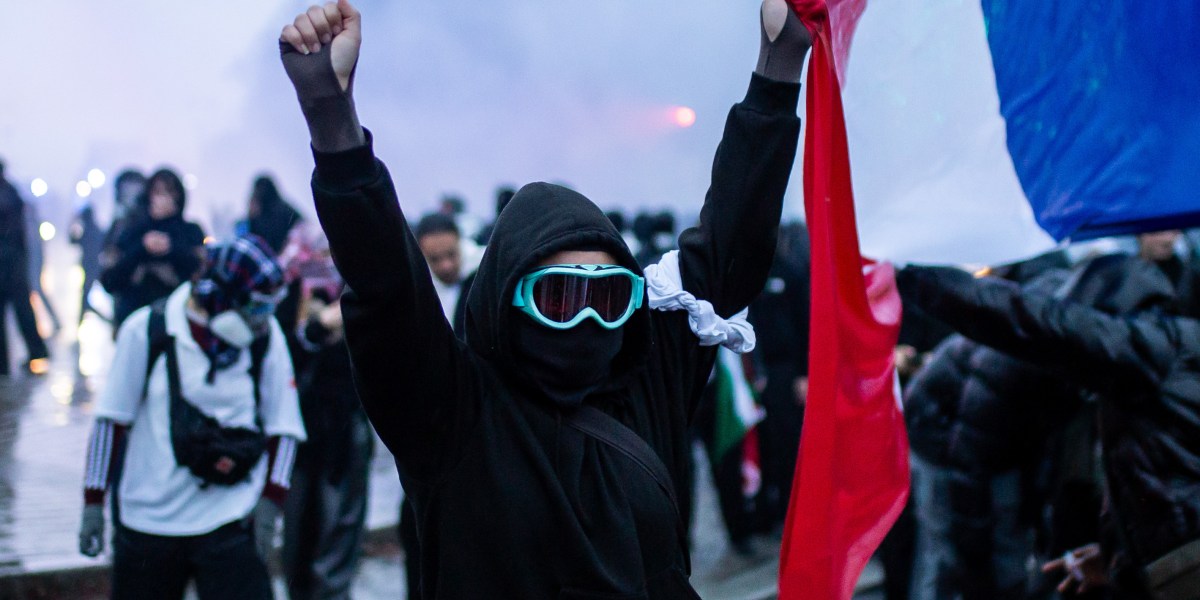
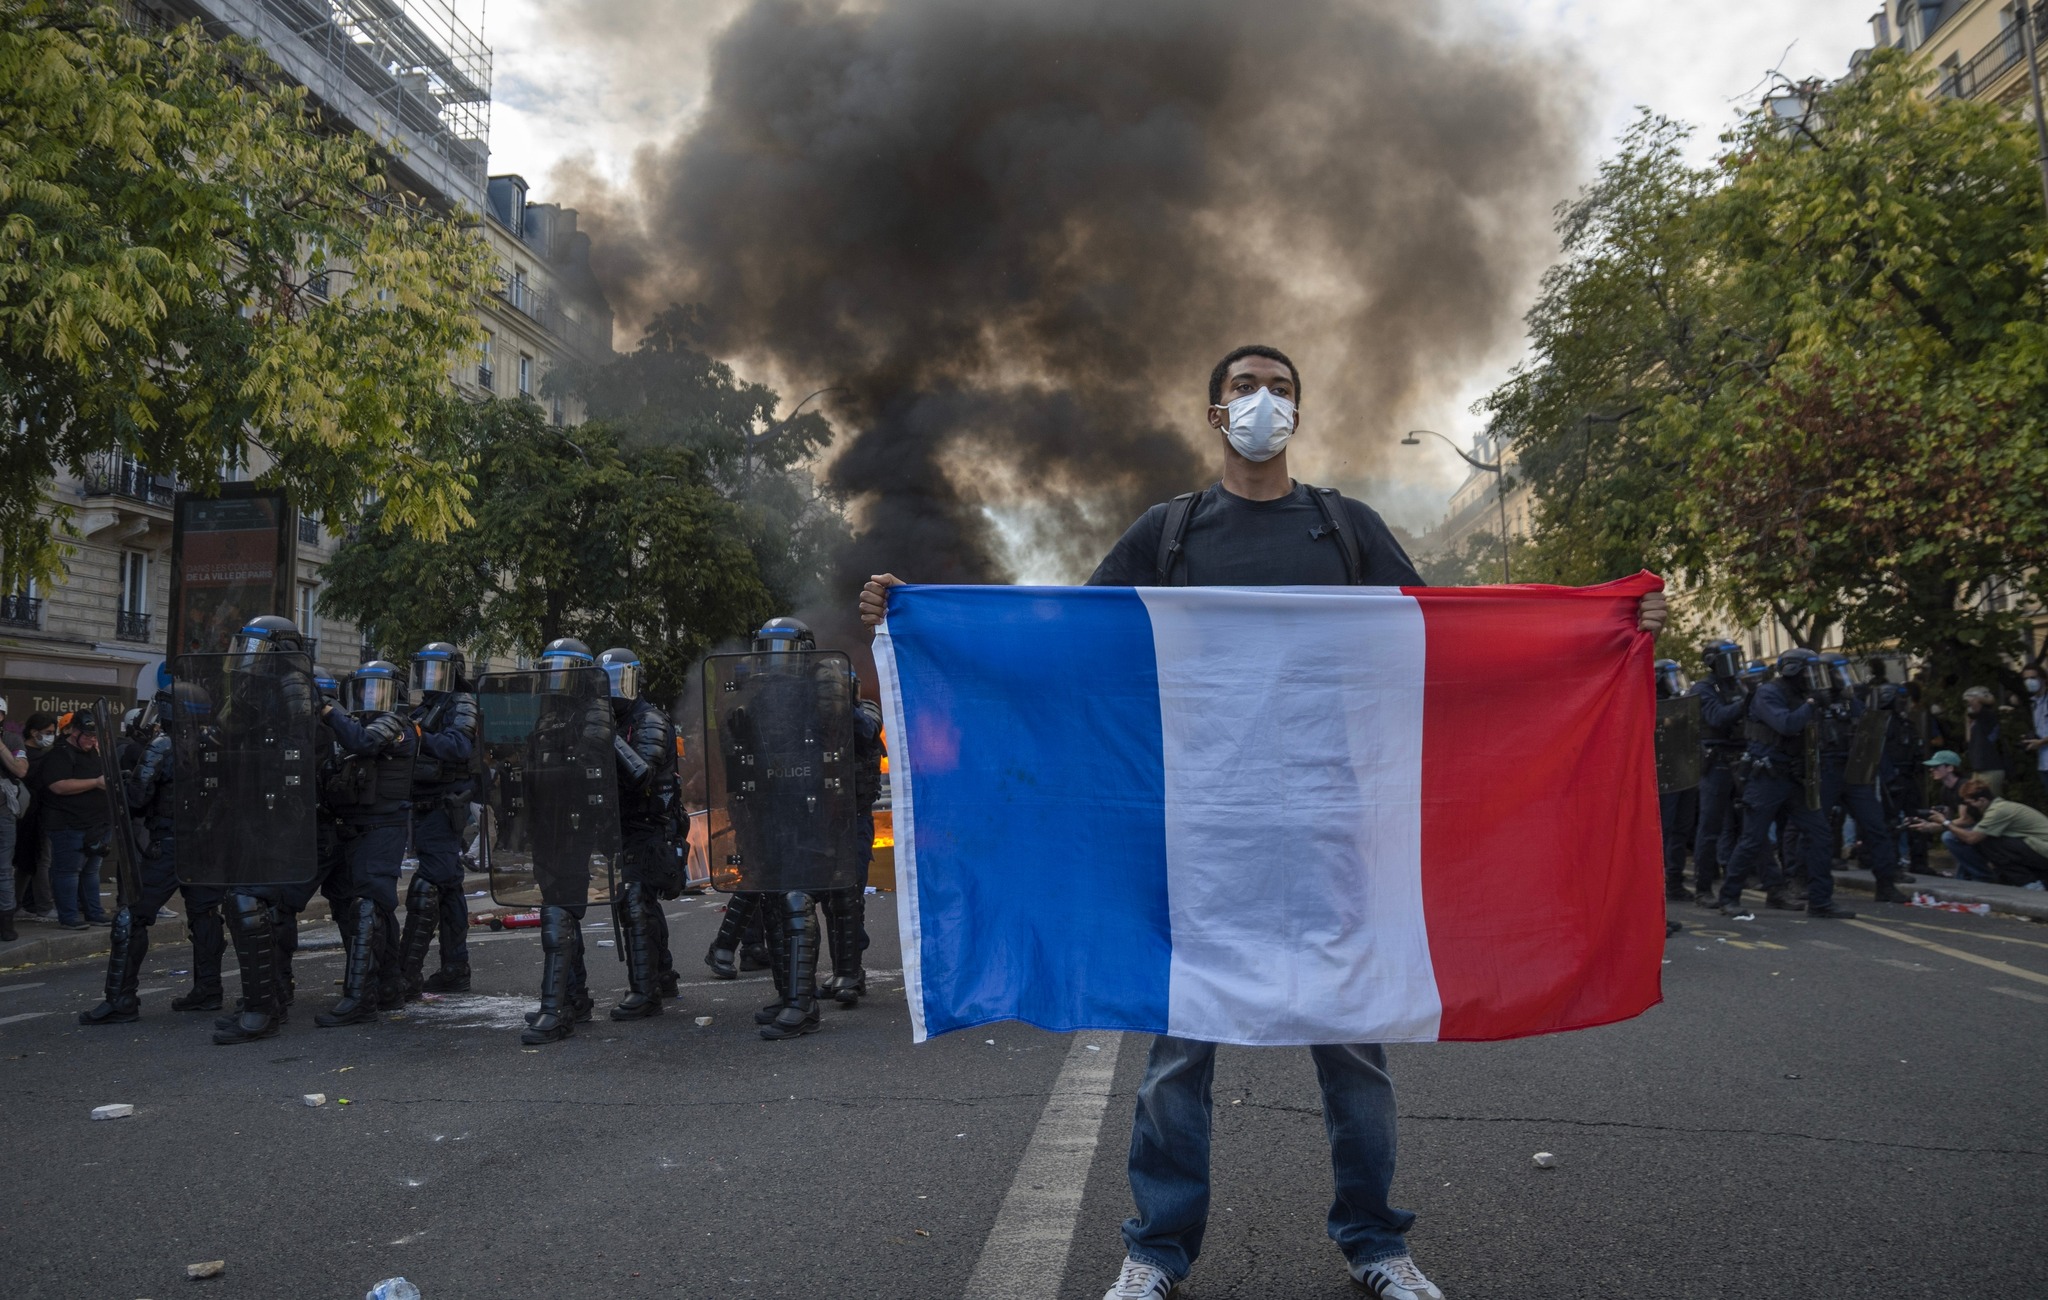
When American financial observers looked on as Paris seemed to come apart at the seams a few weeks back, the prevailing sentiment was a collective “Let’s not do that.” Unrest ripped through the French capital after protesters initially highlighted failings in the public school system, snowballing rapidly into widespread expressions of dissatisfaction with the cost of living and job prospects. The underlying macroeconomic health of the European nation remains under severe strain, with unemployment sitting at 8.3% in Q2, real GDP growth limping at 0.4%, and wage growth restricted to 1.7% nationally. Underpinning it all is a public debt burden at 116% of GDP, with 30-year bonds topping 5.4% at the time of writing.
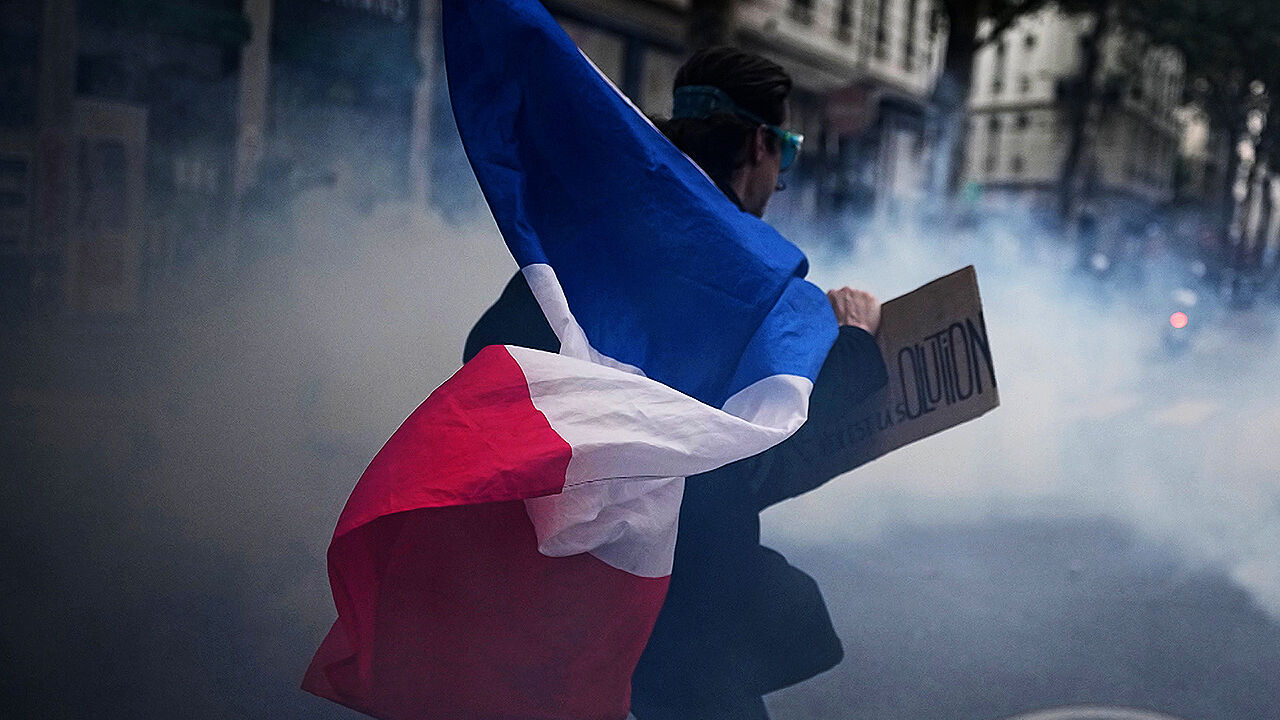
The unrest goes far beyond mere street demonstrations. Around 550,000 individuals took to the streets across France on October 17, 2026, to protest the high cost of living. By nightfall, cars burned in Paris, the town hall in Limoges was set on fire, and hundreds faced arrest during the country’s worst unrest in years. The education minister reported that 24 schools had been burned or ransacked alongside more than 100 severely damaged structures. Behind the immediate violence lies proposed fiscal austerity. The government of Prime Minister Sébastien Lecornu proposed a 2027 budget featuring a €54 billion fiscal adjustment, signaling clear intent to cut government spending rather than expand it. Meanwhile, the French National Assembly unanimously rejected the government’s proposed budget on a Wednesday evening, provoking further fears in the bond market as the budget deficit stood at 5.1%, its worst level in nearly a quarter of a century.
The Bottom Line:
- France’s national debt has climbed to over 115% of GDP, and the budget deficit hit 5.1%.
- Yields on French 10-year OATs surged above 5.13% on October 22, 2026, widening the spread over German Bunds to 174 basis points—the highest level since the early 2000s.
- While U.S. debt sits near 100% of GDP with growth at just over 2%, economists warn that mounting deficits and generational friction foreshadow similar pressures.
French Bond Yields Jump Above Five Percent
Bond market mechanics reveal the true severity of the French trajectory. Following an upward move on October 22, 2026, France’s 10-year OAT yield climbed past 5.13%, while its spread against the German Bund reached 174 basis points to register the widest differential since the early 2000s. Back in February 2026, the French government paid only about 0.6 percent more to borrow than Germany did; by the end of October 2026, it was paying close to 160 basis points more. That rapid expansion means heavily indebted governments must absorb fast-accelerating debt service costs. Burdened by a massive 5,400 trillion won debt pile, France currently confronts an annual interest bill exceeding 100 trillion won.
Investors demand compensation—interest—combining the opportunity cost of capital with a risk premium that reflects the probability of default. With global interest rates remaining elevated, the opportunity cost has climbed significantly. France is among the hardest-hit issuers in the global bond sell-off, with public debt rising from roughly 98% of GDP in 2019 to over 119% by mid-2026. The European fiscal framework is tightening the screws further; the EU Council has asked France to correct its excessive deficit by 2029 while capping nominal growth in EU-defined net expenditure at 1.2% per year between 2026 and 2028.
Diverging Economic Realities Between Paris and Washington
Despite mounting fiscal pressures on both sides of the Atlantic, U.S. bond markets reacted differently as Treasury yields actually eased while French OATs hovered near strain points. Heather Long, chief economist at Navy Federal Credit Union, explained at a Bipartisan Policy Center event that key structural indicators separate the U.S. from France. While the U.S. operates at roughly 100% debt-to-GDP with growth tracking just over 2%, France sits higher on the crisis curve at 120% debt-to-GDP while growing at about 0.5%. France has largely exhausted its revenue-generating capacity through taxes. OECD data shows the tax wedge for French workers—the gap between employer labor costs and employee take-home pay—stands at 47.2%, whereas the U.S. rests at 30%.
That fiscal headroom gives American policymakers more room to maneuver, though long-term structural risks remain. The longer adjustments are delayed, the more the burden shifts unevenly across generations.
Generational Discontent Driving the Next Wave of Fiscal Reckoning
The core warning emanating from Europe involves more than just sovereign spreads and debt ratios. Youth participation in the French protests highlights a deep generational divide over economic opportunity, cost of living, and shrinking career prospects. Students initiating the recent wave of demonstrations demanded 15 trillion won be invested in upgrading school facilities and hiring additional teachers. While the government announced plans to inject 1.5 trillion won annually into educational infrastructure, protesters argue that reversing corporate tax cuts previously enacted by President Emmanuel Macron represents a fairer path to funding public services.

As policymakers in Washington watch these events unfold, the parallels to domestic budget debates grow harder to ignore. Without structural reform, advanced economies carrying historic debt loads risk finding themselves at the mercy of bond vigilantes when market sentiment turns.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.