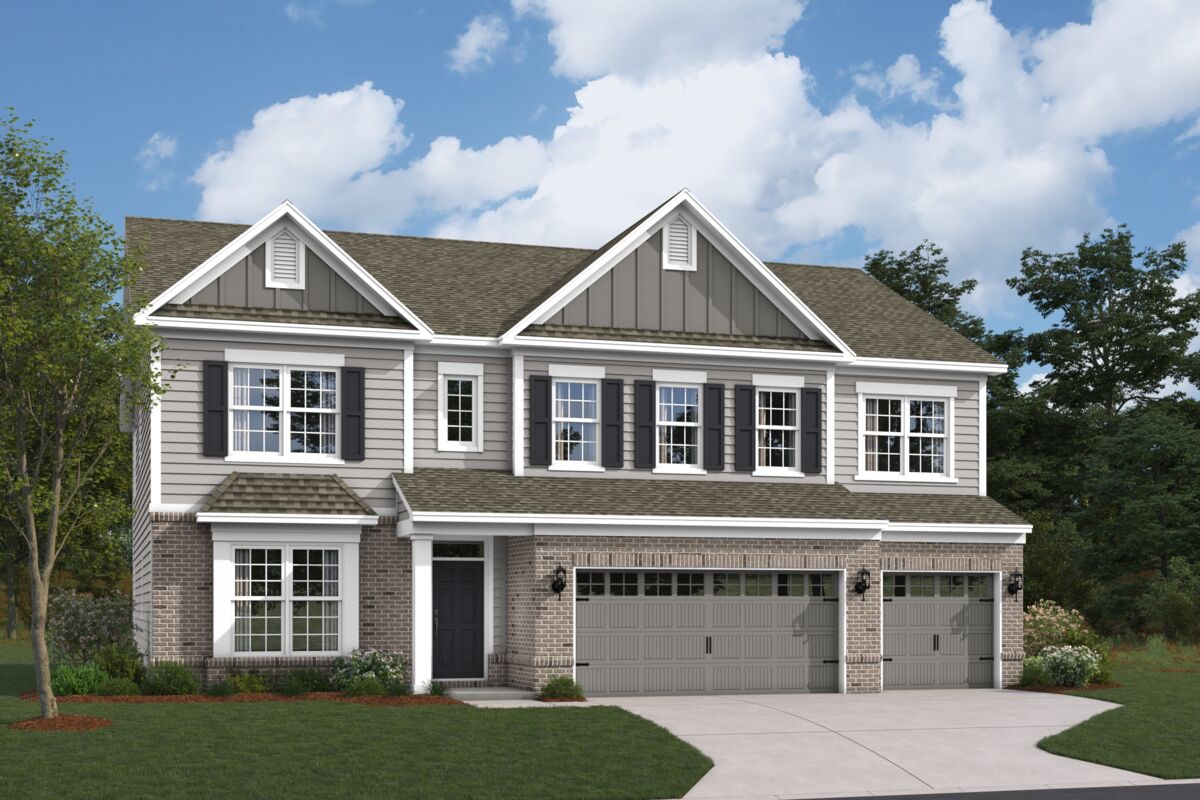
Buying a newly constructed house in Indianapolis comes with a distinct set of financial moving parts this season, particularly for buyers eyeing floor plans like The Lyndale.
The core of the current offering centers on a 30-year fixed-rate FHA loan featuring a 2/1 buydown tied to a promotional interest rate of 5.25 percent. Based on a sample sales price of $349,990, the financing structure requires a 3.5 percent down payment and a minimum credit score of 640. Through this program, the temporary rate reduces to 3.25 percent for the first year, 4.35—or rather, 4.25 percent—for the second year, before settling at 5.25 percent for years three through thirty, producing an annual percentage rate of 6.027 percent.
Secure a Promotional Conventional Loan Rate
For buyers pursuing conventional financing rather than an FHA product, mihomes.com outlines an alternative promotional interest rate of 5.875 percent. This structure is built on a 30-year fixed conventional loan with a 20 percent down payment, utilizing a sample sales price of $397,625 and a loan amount of $318,100.
Under this conventional scenario, the temporary interest rate scales down to 3.875 percent in year one and 4.875 percent in year two, returning to 5.875 percent for the remainder of the term, with an annual percentage rate of 5.997 percent and a minimum credit score requirement of 720.
Alongside these financing mechanisms, buyers may qualify for up to $5,000 in paid closing costs. This contribution covers allowable buyer expenses, prepaid items, and capital contribution fees up to 3 percent of the sales price, though it specifically excludes discount points, future homeowner association dues, and fees associated with independent home or radon inspections.
Meet Strict Financing Deadlines
These promotional rates and closing cost contributions are not open-ended. The programs apply strictly to new contracts written on or after September 14, 2026, and exclude cancellations, property re-writes, or contract transfers.
Time is a critical constraint for interested buyers reviewing these options. Program guidelines mandate that the buyer submit a formal loan application within 48 hours of contract signing. All transactions tied to these specific promotional rates must close by December 22, 2026. Financing is offered through M/I Financial, LLC, and maximum allowable county loan limits apply alongside standard agency restrictions.