Wilmington Businesses Evaluate Operational Changes and Map Upcoming Investments at Year-End
Year-end brings a familiar cadence for business owners across the Wilmington area. Financial statements land on desks, tax discussions climb priority lists, and budgets get a hard second look as cash flow takes center stage.
For Wilmington businesses, these routine calendar adjustments shape how companies approach the year ahead. According to reporting from wilmingtonbiz.com, year-end offers more than a simple accounting deadline. It provides a distinct window to evaluate operational changes over the previous 12 months, pinpoint financial pressure points, and map out upcoming capital investments.
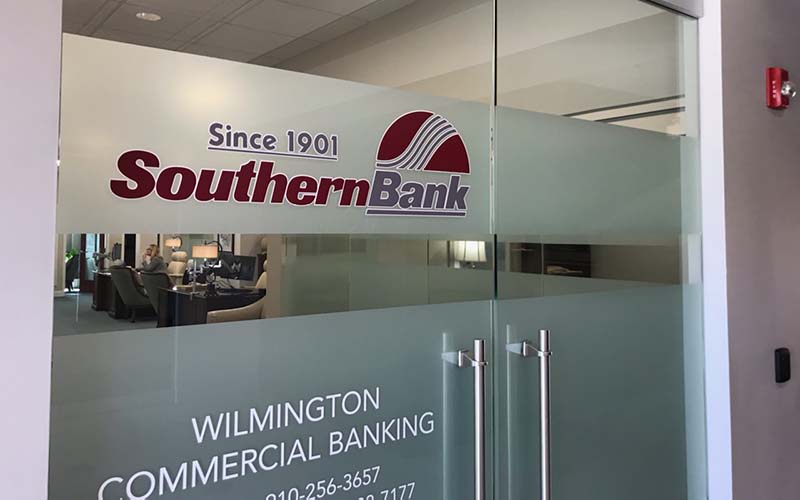
Southern Bank approaches these client conversations with a long-term perspective. By understanding how a business operates across all four quarters, year-end planning shifts from reacting to a single monthly snapshot into contextualizing the company’s full financial picture.
Looking Beyond the Closing Balance Sheet
A standard year-end review begins with the numbers, but the most actionable questions dig deeper into operational rhythms. Business owners must ask whether revenue arrived on schedule, if expenses aligned with incoming payments, and whether growing administrative demands strained internal accounting processes.
Sufficient working capital remains essential for funding future opportunities. Analyzing these transactional patterns helps operators identify where daily financial operations succeed and where adjustments are necessary.
Jennifer Robbins, owner of the Wilmington-based outdoor living design and installation company Backyard Specialist, found unexpected value by reevaluating her everyday banking setup. I had no idea that I wasn’t happy with my bank, but then when I saw all that [Southern Bank] could offer — it was incredible to get interest on my business checking account. It’s like found money,
Robbins says. She notes that adopting remote deposits also streamlined cash management.
Routine operational updates directly influence how efficiently a company manages cash. Clear visibility into money movement positions owners to plan effectively for what comes next.
Managing Cash Flow Through Seasonal Shifts
Profitability and cash flow run on separate tracks. A business can post a strong annual profit while still experiencing tight stretches where customer payments, payroll, material costs, and vendor expenses fall out of sync.
For seasonal and project-based enterprises, those timing gaps carry heavy weight. Year-end allows owners to review historical cash flow data, identifying precisely when balances dipped and when reserves strengthened.
That retrospective review uncovers opportunities to optimize deposit processes, put idle cash to work, and build working capital reserves ahead of demanding operational cycles. Southern Bank’s approach focuses on understanding the path a business took to reach its year-end figures, ensuring future capital decisions match broader operational realities.
Capital Planning Before Urgent Needs Arise
Year-end also brings next year’s larger capital priorities into focus. Companies evaluating new equipment purchases, expanded staffing, or facility upgrades need runway to assess how those investments impact existing cash reserves and debt obligations.
Capital planning extends beyond checking whether financing is available. Investment timing, accessible cash cushions, and competing priorities shape the correct financial approach.
Southern Bank’s business banking strategy is built to evolve alongside growing companies. Initiating financial conversations before an immediate need arises gives owners the space to evaluate options methodically.
Maintaining Continuity Across the Business Cycle
No single month captures the full story of an enterprise. A December balance sheet misses a February seasonal slowdown, a major June project win, or a September equipment purchase.
Continuity in business banking prevents owners from having to re-explain their operations every time a new financial need surfaces. Past performance informs future decisions when a banking partner observes those shifts firsthand.
For Robbins, that stability is reinforced by her bank’s deep roots. I can’t believe y’all are going to have 125 years [of business],
she notes, referencing Southern Bank’s history dating back to its 1901 founding. That makes me feel good as a customer because I know that you’re going to continue to be around.
Founded in 1901, Southern Bank operates as a wholly owned subsidiary of Southern BancShares (N.C.), Inc. Headquartered in Mount Olive, North Carolina, the institution manages over $5 billion in total assets across more than 60 locations in eastern North Carolina and Virginia.
Ultimately, year-end planning is about carrying lessons, financial patterns, and operational relationships from one year into the next. For Wilmington businesses, sustainable stability means reading the big picture clearly and securing the right support to decide what comes next.