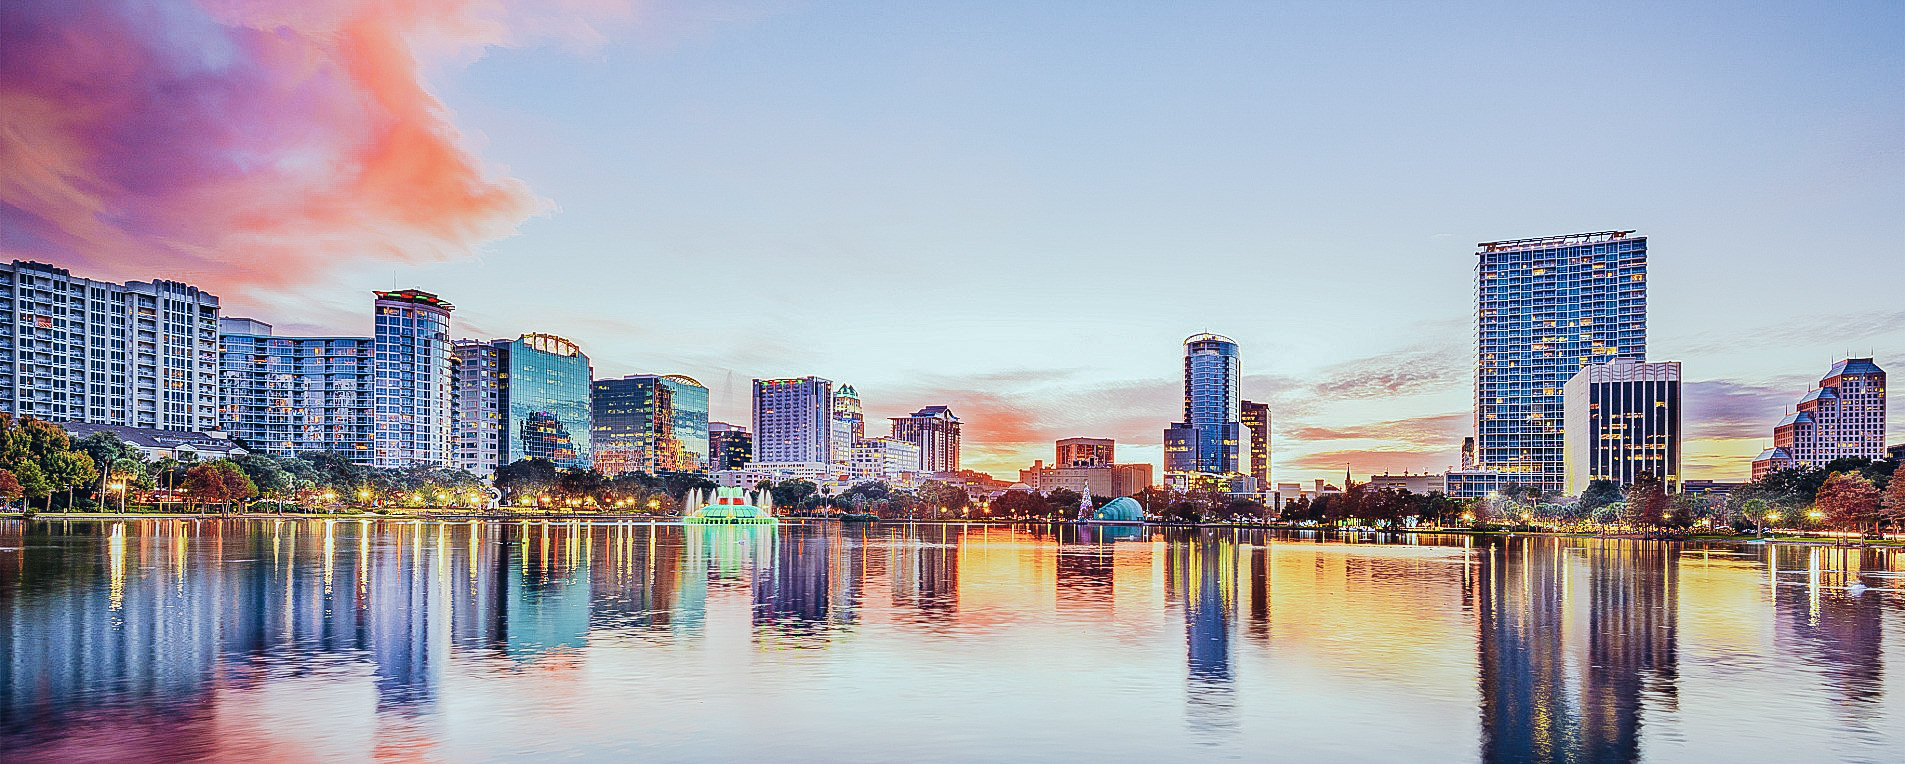
Orlando's retail market is experiencing a sharp divergence between high leasing costs and moderating tenant demand, even as investors pour capital into neighborhood centers and general retail spaces across the metro area.
Matthews reported that the local retail market absorbed 107,000 square feet in the third quarter of 2026, marking a steep drop from the 679,000 square feet absorbed during the same period in 2025. This cooling demand pushed vacancy up to 3.8 percent, which is 14 basis points looser than the third quarter of 2025. Trailing-12-month absorption stands at 550,000 square feet, sliding down from 961,000 square feet the year prior.
Supply Constraints Shape Leasing Realities
While demand slows, new construction remains heavily restricted, creating a distinct pinch for expanding retailers. Cushman & Wakefield noted that developers delivered nearly 1.0 million square feet over the past 12 months, leaving only 73,700 square feet still available for lease. Dick’s Sporting Goods and Total Wine & More captured the largest share of those recent deliveries.
At the same time, roughly 835,000 square feet remained under construction across 42 properties, with 65 percent of that pipeline preleased. The Osceola Outlying submarket holds the largest pipeline at 274,000 square feet, followed by Downtown Orlando at 126,000 square feet and the NW Orange Outlying submarket at 99,000 square feet. Meanwhile, the Lake Nona West submarket features the largest single project underway: a 405,000-square-foot community center anchored by Target and Nordstrom Rack.
Matthews pointed out that space currently under construction equals just 0.5 percent of total inventory, concentrated heavily in Downtown Orlando at 8.0 percent of its stock. Contrast that historical peak in annual deliveries, which hit 5.83 million square feet back in 2007, with the third quarter of 2026 deliveries of 110,000 square feet—less than half of the 349,000 square feet delivered in the third quarter of last year.
Diverging Performance Across Property Types
Total leasing volume declined slightly year-to-date, down from the 4.1 msf leased during the same period one year ago. Cushman & Wakefield reported that malls, power centers, and strip centers shed space on net, recording occupancy losses of roughly 214,000 square feet, 135,000 square feet, and 116,000 square feet respectively. Those losses pushed mall vacancy to 7.0 percent and power center vacancy to 6.8 percent.
Despite those occupancy losses in traditional centers, pricing climbed steadily. Matthews calculated average asking rents at $31.17 per square foot, marking a 2.5 percent increase year-over-year and sitting within 1 percent of the $31.18 peak reached in the second quarter of 2026. Cushman & Wakefield put the average slightly higher at $31.19 per square foot, noting a 2.6 percent annual growth rate that outpaces the 1.7 percent national average. Among property types with over 10.0 msf, power centers led growth at 3.5 percent year-over-year, while malls commanded the highest asking rents at $43.69 per square foot.
Investment Sales Rebound Against Tightening Caps
Investor appetite in Orlando’s retail sector remains resilient, driven by population growth, tourism spending, and consistent rent gains. Matthews reported trailing-12-month sales volume reached $1.9 billion, a 29 percent jump compared to the prior trailing period, with the third quarter alone accounting for $473 million. That figure surpasses the series peak of $1.8 billion set in 2022.
Cushman & Wakefield offered a slightly more focused view on year-to-date figures, tracking sales volume at approximately $1.4 billion across 444 transactions, nearly matching the $1.5 billion recorded for the full year of 2025. General retail and neighborhood centers accounted for roughly 86 percent of that transaction volume, led by general retail at $772 million across 316 transactions. Neighborhood centers followed with $464 million across 76 deals.
| Metric | Matthews Data | Cushman & Wakefield Data |
|---|---|---|
| Average Asking Rent | $31.17 / SF (+2.5% YoY) | $31.19 / PSF (+2.6% YoY) |
| Vacancy Rate | 3.8% (+14 bps YoY) | Not specified |
| Sales Volume | $1.9B (TTM, +29% YoY) | $1.4B (YTD) |
| Average Cap Rate | 6.68% | 6.7% |
| Average Price / SF | $303 | $284 |
Pricing across the metro averaged $303 per square foot according to Matthews. Cap rates averaged 6.68 percent, compressing for four quarters and sitting 63 basis points below the first-quarter 2015 high of 7.31 percent. Meanwhile, Cushman & Wakefield noted average pricing at $284 per square foot, highlighted by transactions like the $72.3 million sale of a 175,000-square-foot property at 5725 Major Boulevard in the first quarter of 2026, and the Shoppes at Hammock Ridge changing hands at $18.5 million, or $607 per square foot, in the third quarter.