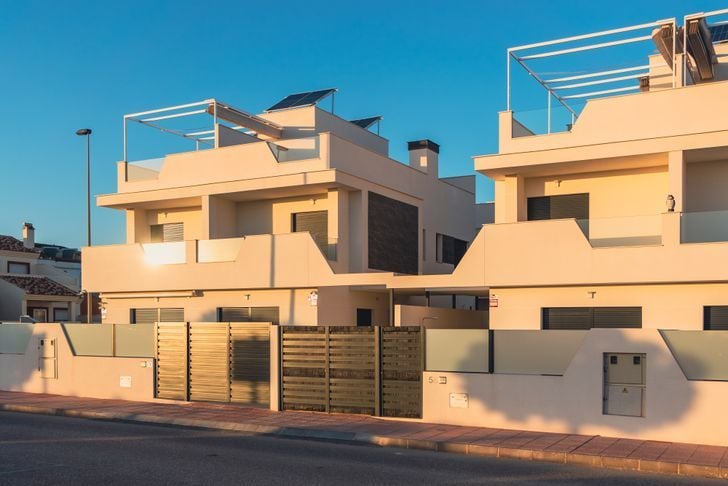
Vilnius property developers face a growing backlog of unsold townhouses that could take nearly three years to clear, even as broader housing demand in the capital holds near historical norms according to October 2026 market data.
Vilnius Townhouse Supply Climbs While Buyer Interest Slips
The Vilnius primary housing market saw developers agree on 470 apartment, loft, and townhouse sales in October 2026, according to figures from Citus. That total marks a 0.8 percent dip from September and a 19.8 percent drop compared to the same month last year. In contrast, Inreal reported 458 total transactions for the city that month—comprising 490 new agreements and 32 cancellations—which was slightly up from 432 in September but roughly 8 percent lower than the 499 recorded in October 2025. Meanwhile, Realco sales director Marijonas Chmieliauskas estimated that 426 newly built apartments were sold in the capital during October. Despite the differing tallies, the broader monthly sales pace tracks closely with the capital’s long-term average of roughly 475 units per month.
Behind those steady headline figures, the townhouse segment has hit a distinct speed bump. October brought 140 newly built townhouses to the Vilnius market, pushing total unsold inventory of this housing type to 451 units—the highest level recorded since July 2025. Buyer demand has moved in the opposite direction.

Clearing the current townhouse backlog would require nearly three years. Across the wider residential inventory, buyers in the capital could choose from 5,277 total homes at the end of October, representing a 17 percent increase over the previous year.
Apartment Sales and Pricing Shifts Across Housing Classes
Separate industry figures from EIKA Development show that 301 new apartments were sold in the capital during October 2026, marking a 28 percent decline from September and a 36 percent decrease from October 2025. EIKA Development department director Tomas Žiaugra noted that October sales figures could signal a cooling of buyer interest, though he cautioned that a single month of data is insufficient to establish long-term trends. Žiaugra pointed to increased housing inventory, uncertainty surrounding interest rates, and political turbulence overseas stemming from the U.S. mid-term elections as factors that heighten buyer caution and lengthen decision-making times. The city’s primary market added 186 new apartments in October, cutting new supply in half compared to the same month last year.
Market segmentation reveals starkly divergent paths for different price tiers:
- Economic-class apartment sales rose 23 percent month-over-month to 179 units.
- Mid-range apartment sales dropped nearly 60 percent from September to 101 units.
- Prestigious-class sales remained essentially flat at 21 units compared to 22 in September.
Overall average square-meter prices in Vilnius dipped 0.3 percent in October from 4,164 euros to 4,151 euros, though annual price growth remains above 7 percent. Market analysts note that the monthly price easing stems from project completion cycles and flexible pricing on remaining unit inventories rather than sweeping discount campaigns. At the same time, October price reduction cases outnumbered increases for the first time in 15 months as developers holding larger portfolios adjusted to softening demand, according to Tomas Sovijus Kvainickas, head of investment and analysis at Inreal Group.
Diverging Trends in Kaunas and Klaipėda
While the capital grapples with a townhouse glut, secondary cities are charting different courses. In Kaunas, developers recorded 117 residential sales in October, up 12.5 percent from September but down 1.7 percent annually. The average price per square meter in Kaunas reached 3,535 euros, delivering a 14.7 percent annual price jump that outpaces growth in Vilnius.
In the Klaipėda market, total unsold inventory held stable at 808 units, while the average square-meter price stood at 3,670 euros, marking a 14.5 percent annual increase.