German Industrial Orders Miss Growth Targets
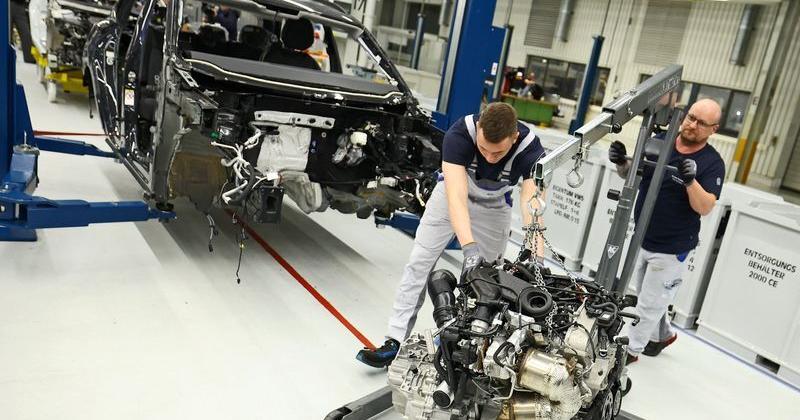
German industrial orders rose by 4.4% in September, a rebound that nonetheless fell short of the 4.8% growth anticipated by analysts in a Reuters poll. While the Federal Statistical Office reported a return to positive territory following a revised 10.1% decline in August, the data indicates that Europe’s largest economy remains in a precarious state of recovery. Official data reported that the September increase was heavily reliant on the automotive sector, which surged 10.5% after months of factory holidays and production changeovers. The Bottom Line:
- September orders rose 4.4% month-over-month, trailing the 4.8% consensus estimate.
- The automotive industry drove the bulk of the volume with a 10.5% gain, while machinery and equipment orders added 8.3%.
- Manufacturing orders for the third quarter remained nearly flat, showing only a 0.2% increase compared to the second quarter.
Automotive and Machinery Sectors Drive September Growth
The uptick in September activity was concentrated in specific, high-volatility segments. According to data provided by UA.News, the automotive industry and the machinery sector accounted for the primary growth, while other transport equipment—a category encompassing aircraft, trains, and military hardware—saw a sharp 10.4% decline. The VDMA industry association noted that while mechanical and plant engineering orders rose 14% year-over-year, this figure is skewed by an exceptionally weak comparison period in 2025. Consequently, industry leadership remains cautious, viewing the current upswing as tenuous rather than a structural shift in demand.
Euro Trims Gains as Crude Prices Plummet
The release of these figures had an immediate impact on currency markets. FXStreet reports that the Euro (EUR) trimmed gains against the US Dollar (USD), pulling back from session highs near 1.1270 to trade just below 1.1250. This volatility occurs against a backdrop of shifting commodity prices; the price of Brent crude plummeted approximately $20 over the last 48 hours to near $93.00. This decline in energy costs provides a necessary fiscal buffer for Eurozone importers, though it has not yet been sufficient to fully insulate German manufacturing from broader macroeconomic headwinds.
The divergence between manufacturing output and service sector resilience continues to complicate the European Central Bank’s path. While energy price relief is a tailwind, the underlying fragility in industrial demand suggests that the European Central Bank must balance inflation suppression against the risk of deepening the manufacturing slump.
Impact on the American Consumer
For the average American, the sluggishness in German manufacturing carries indirect but significant weight. As Germany serves as a primary engine for the Eurozone economy, sustained weakness in its industrial sector limits the growth potential of major US trading partners. This can manifest in diminished demand for American exports and, more critically, in the stability of global supply chains. Institutional investors are closely monitoring these figures as a proxy for global industrial health. When German orders miss expectations, it often signals a cooling in global capital expenditure, which can influence the valuation of multinational firms in 401k portfolios and broader equity indices.
The Inflationary Conflict
The European Central Bank faces a complex mandate. Despite the industrial slowdown, consumer inflation in the Eurozone accelerated to a 4% year-on-year pace in October. This creates a difficult environment where the central bank is pressured to maintain high interest rates to combat inflation, even as the manufacturing base struggles with the cost of liquidity. Market participants are tracking these developments closely, as any deviation in ECB monetary policy could trigger shifts in the yield curve that influence global borrowing costs.
The current data from the Federal Statistical Office confirms that the industrial sector is not yet operating at a capacity that would sustain long-term, non-inflationary growth. Whether the October and November periods show a stabilization of these orders remains the primary question for investors, as the current reliance on volatile automotive cycles leaves the manufacturing sector vulnerable to further shocks.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.